The Role of Support and Community in Building Financial Confidence
Money confidence is often described like a private skill, almost like learning to swim alone in the deep end. People are told to read more, budget better, cut spending, and become more disciplined. That advice is not wrong, but it misses something important. Most people do not lose confidence with money because they lack information. They lose confidence because money decisions are stressful, emotional, and tied to identity, family history, and fear of getting things wrong.
That is why support matters so much. Financial confidence grows faster when people are not carrying every decision by themselves. A conversation with a trusted friend, a community workshop, or a mentor who has already made similar choices can make money feel less mysterious and less intimidating. Even big decisions, like whether a home equity loan fits into a larger financial plan, become easier to evaluate when someone can help ask clear questions and slow the process down.
Community changes the feeling of personal finance from performance to practice. Instead of treating money like a test you either pass or fail, support systems make it feel like something you can improve over time. That shift matters more than many people realize, because confidence is rarely built in one dramatic moment. It is built through repeated experiences of making a choice, learning from it, and realizing you can handle the next one too.
Why money confidence is emotional, not just mathematical
A lot of financial advice assumes that people freeze because numbers are confusing. Sometimes that is true, but often the bigger issue is emotional pressure. Bills can trigger shame. Debt can trigger panic. Investing can bring up fear of loss. Asking for help can feel embarrassing, especially in a culture that treats money as a sign of competence.
When people try to solve all of that in isolation, their stress can grow louder than any spreadsheet. A supportive environment softens that pressure. It gives people room to say, “I do not know what to do here,” without feeling judged. That emotional safety is a serious advantage. It makes it easier to ask basic questions before a problem gets bigger.
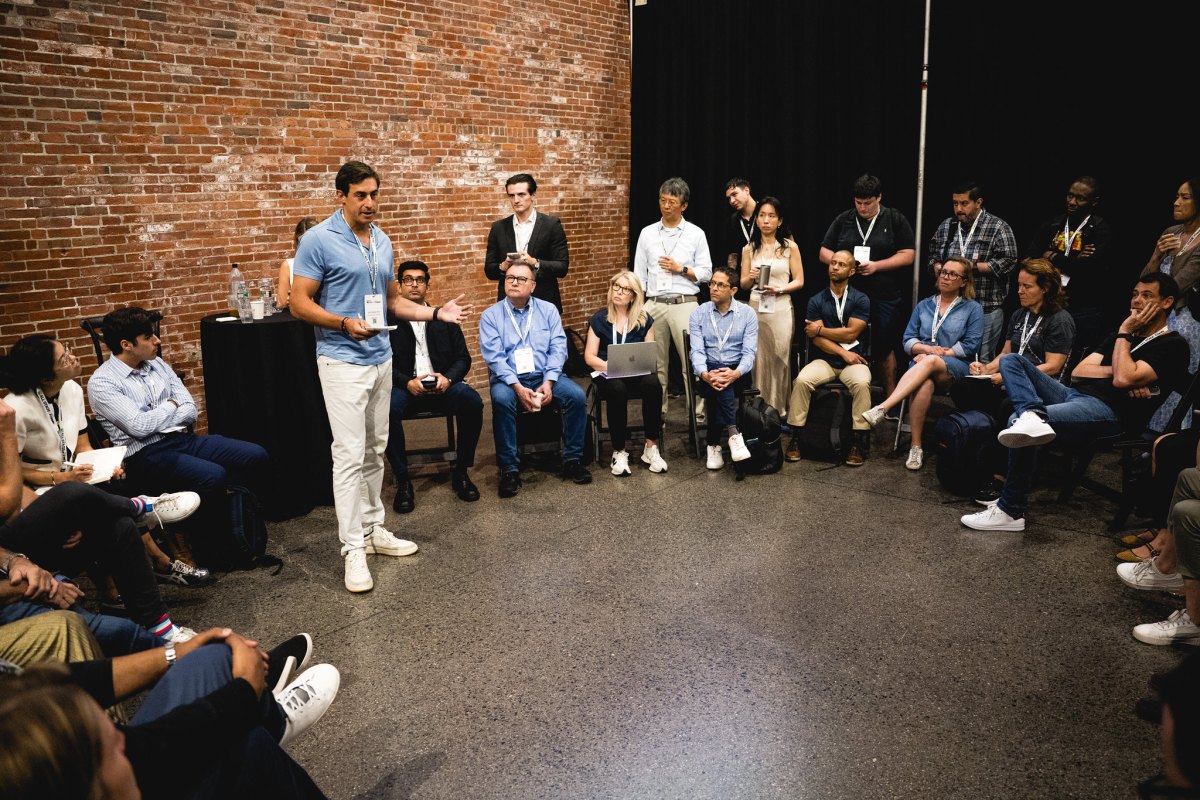
This is one reason peer based support can be so powerful. In a small group, people often realize their struggles are common. The surprise medical bill, the overspending during stressful months, the uncertainty about credit, the hesitation around homeownership, all of it becomes less personal and more manageable when others nod and say, “I have dealt with that too.”
The quiet power of being seen
One of the most underrated parts of community support is recognition. People build confidence when someone notices progress that they might overlook on their own. A friend might point out that you paid down a credit card for three months in a row. A coach might remind you that calling a lender, comparing offers, or finally checking your account balance regularly is real progress.
That kind of feedback matters because money goals are usually slow moving. You may not feel different after one week of better choices. But when someone reflects your growth back to you, it becomes easier to believe that you are changing. Confidence often arrives after evidence, and community helps people spot the evidence sooner.
Mentorship can play a similar role. A mentor does not need to be wealthy or perfect. In fact, people often benefit most from someone who has made mistakes, recovered, and learned practical lessons. That person can offer grounded advice instead of polished theory. They can say what helped them rebuild savings, negotiate bills, or stay calm during setbacks. That kind of lived wisdom is hard to replace.
Accountability works better when it feels human
Many people hear the word accountability and immediately think of pressure. But healthy accountability is not about guilt. It is about being connected to someone who helps you stay honest and consistent.
When a person sets a financial goal alone, it is easy to delay it. Life gets busy. Motivation dips. One rough week turns into a rough month. But when someone else knows the goal, whether it is paying off a balance, building emergency savings, or reviewing a budget every Sunday, the goal becomes more real. It moves from a vague intention to a shared commitment.
This is one reason financial coaching models have drawn attention in community settings. Research from the Urban Institute highlights how financial coaching uses regular, one on one sessions to help people set goals and follow through with practical action steps. That structure can help turn financial knowledge into behavior because someone is there to check in, adjust the plan, and keep the person moving forward with purpose instead of shame. financial coaching programs can be especially useful for people who need both strategy and encouragement.
The key is tone. Accountability without compassion can make people avoid money conversations altogether. Accountability with empathy does the opposite. It helps people return to the plan after a setback instead of abandoning it.
Practical wisdom travels through communities
Formal education teaches concepts. Community often teaches application. That difference is huge.
A person may understand interest rates in theory and still feel unsure about comparing loan offers. They may know they should ask questions before accepting financial terms but not know which questions matter most. In a community setting, people learn from examples, stories, and shared experiences. They hear what surprised others, what red flags to watch for, and what habits helped make a plan sustainable.
That practical wisdom is especially important during life transitions. Starting college, changing careers, caring for family, buying a home, or recovering from job loss can all create financial uncertainty. During those times, support from institutions and local networks can make a real difference. The U.S. Department of Education, for example, encourages students to work with their school’s financial aid office when aid is not enough and to explore help from community organizations and local foundations. Those kinds of support channels remind people that financial problem solving is not always a solo task. school financial aid office guidance can open up options that someone might miss on their own.
Confidence grows when help is normalized
The healthiest communities do something simple but powerful. They normalize asking for help before a crisis. That one cultural shift can change financial outcomes.
If support is only seen as something for people who are already overwhelmed, many will wait too long. But when money conversations are treated as normal, like asking for a recipe or workout advice, people engage earlier. They ask questions sooner. They compare options more carefully. They make fewer decisions from panic.
This also helps break the cycle of secrecy that keeps many people stuck. Silence can make financial struggles feel unique and permanent. Community reminds people that setbacks are part of life, not proof of failure. That mindset creates resilience, and resilience is one of the strongest foundations for confidence.
Building your own money support system
Not everyone has a built in circle for money conversations, but support can be created intentionally. Start small. Identify one trusted person who is calm, practical, and not overly judgmental. Join a local workshop, online education group, or coaching program. Look for people who respect facts, encourage thoughtful decisions, and understand that progress is usually uneven.
It also helps to choose support that matches the moment. Sometimes you need emotional reassurance. Sometimes you need technical guidance. Sometimes you just need someone to sit with you while you open the bill, review the numbers, and take the next step.
Financial confidence does not come only from mastering money. It comes from learning that you do not have to face every financial decision alone. The more people feel supported, informed, and connected, the more likely they are to act with clarity instead of fear. In that sense, community is not just a nice extra. For many people, it is the very thing that turns financial knowledge into financial courage.